Showing posts with label economic growth. Show all posts

Wednesday, November 07, 2007

Romer Rules!


Paul Romer of Stanford University is one of my favorite economists. Romer is the founder of Aplia and a pioneer in the new growth theory that was discussed in Chapter 8 of your e-book. Romer’s father, Roy Romer, was the former Governor of Colorado and the Superintendent of the LA Unified School District. I was fortunate to have dinner with Paul Romer a few years back and I can tell you in spite of his brilliance he is a truly nice guy. I have no doubt that he will win the Nobel Prize in economics for his contributions to growth theory.

To learn more about Romer’s work on economic growth see David Warsh's book Knowledge and the Wealth of Nations , or look at the Economist article "The Growth of Growth Theory" in its 18 May 2006 issue. . You can also listen to a recent podcast interview with Romer in the excellent EconTalk series hosted by Russ Roberts. Or alternatively you can read the transcript of the EconTalk interview with Professor Romer.

Once macro minds start thinking about economic growth it is hard to think about anything else. You may want to consider a topic relating to economic growth as the subject of your Discussion Board posting.

Extra Credit: Address the question: Is Aplia an effective tool for improving student learning? Do the Aplia homework assignments increase your learning potential? I don’t want to hear whining that the questions in Aplia are hard. The questions on Aplia may seem hard, but they are not any harder than they would be in any standard transferable economics course. What I want to know is if you think that Aplia is a technology that leads to better educational outcomes. What do you like about Aplia? What are its weaknesses? Do you have any suggestions for improvement? Aplia’s pitch to professors is that the students do more work and the professor does less. I am also interested in knowing what other techniques that you think are useful to create a successful online learning environment. I have set up a forum on the Discussion Board called Aplia Forum. I will give between one and four points for every thoughtful post on Aplia and creating a thriving online learning environment. One post per student please. The number of points that you will be awarded to your Discussion Board Extra Credit account depends on the length and quality of your post. To earn the maximum of four points your post should be thoughtful and several paragraphs in length.

Friday, November 02, 2007

GDP up more than expected


In Chapter 7 of your e-book, you are learning about the main macro measure: gross domestic product or GDP. GDP helps us to measure the performance, speed, and health of the macroeconomy. Looking at the path of real GDP allows us to evaluate our monetary and fiscal policies, our investment and savings patterns, and our material well being.

This week there was good news on the GDP front. The first estimate of third quarter economic growth was better than most economists (including myself) had expected. The Bureau of Economic Analysis reported this week that U.S. real GDP grew at a 3.9% annual rate in the third quarter.
The most common way to calculate GDP is to add up all spending on domestically produced final goods and services, leading to the equation GDP = C+I+G+X-IM. There was good growth in nonresidential fixed investment (I) helping to make up for the weakness in housing. There was also good growth in exports (X) because of the weak dollar. I am still trying to figure out why consumer spending grew at three percent! Government purchases grew by 3.7 percent at annualized rate almost entirely because of defense spending growth.

Click here for a sample of the reactions of various economists to the latest GDP report, and here for a detailed analysis of the GDP picture. Anyway if GDP growth is so could why did the Fed feel the need to cut interest rates this week? Do they know something that isn’t in the stats?

Extra Credit: Why does the BEA Press Release refer to real GDP? Is there a fake GDP? Explain. How much did the GDP deflator rise in the third quarter? If you are the first student to send me an e-mail (kwoodward@saddleback.edu) with the answer, you will be rewarded with two extra credit Discussion Board points. Only two points extra credit per student can be earned in any given week from the blog questions.

Tuesday, October 16, 2007

The Recent Financial Turmoil and its Economic and Policy Consequences


Yesterday on Monday, October 15 Federal Reserve Chairman, Ben Bernanke, gave a speech that seemed to scare stock markets throughout the world. In his speech to the Economic Club of New York Bernanke seemed much more nervous about problems in the housing market than in previous speeches, calling the housing slump a “significant drag” on growth into next year, and the outlook for the economy “uncertain.” Bernanke tried to assure the financial markets that the Fed will “act as needed” to maintain economic growth. You will be learning a lot more about the Federal Reserve System and monetary policy when we cover Chapter 13 in your text. You can watch the video of the Bernanke speech about the current state of the economy on Bloomberg or read the transcript here.
Speaking of the Fed last week Bernake gave an important speech the US Chamber Education and Workforce Summit. In this speech Chairman Bernake spoke about the value of education, calling it the “best investment.” He stated, “the benefits of education are more than economic. A substantial body of evidence demonstrates that more-highly-educated individuals are happier on average, make better personal financial decisions, suffer fewer spells of unemployment, and enjoy better health.”

Bernanke starts his education speech by saying: When I travel around the country, meeting with students, business people, and others interested in the economy, I am occasionally asked for investment advice. Usually (though not always) the question is posed in jest. No one really expects me to tell them which three stocks they should buy. However, I know the answer to the question and I will share it with you today: Education is the best investment. “

You can Read Bernake’s education speech online at :http://www.federalreserve.gov/newsevents/speech/bernanke20070924a.htm

Examining the role of education in economic growth would be a worthwhile topic for your post, and might serve to keep you motivated to do well in the course.


Fall Late Start Extra Credit: Where did Ben Bernanke teach economics before becoming Chair of the Federal Reserve? What was Bernanke’s main area of research when he was an academic? Explain and cite your source. If you are the Fall late start student to send me an e-mail at kwoodward@saddleback.edu with the answer, you will be rewarded with two extra credit Discussion Board points. Only one blog extra credit question per student can be answered in any given week for Discussion Board extra credit

Saturday, June 16, 2007

More Growth Needed?


Summer school in Macroland starts in a few days. For the summer session I am trying out a new Aplia e-book by Paul Krugman and his spouse, Robin Wells. In addition to being one of the most highly regarded economic theorists, Krugman also writes an interesting and sometimes very partisan economics column for the New York Times. Krugman's latest column is most interesting:


June 15, 2007


Op-Ed Columnist


America Comes Up Short


By PAUL KRUGMAN


LONDON


Traveling through Europe recently, I've been able to confirm through personal experience what statistical surveys tell us: the perceived stature of Americans is not what it was. Europeans used to look up to us; now, many of them look down on us instead.

No, I'm not talking metaphorically about our loss of moral authority in the wake of Guantánamo and Abu Ghraib. I'm literally talking about feet and inches.

To the casual observer, Europeans — who often seemed short, even to me (I'm 5-foot-7), when I first began traveling a lot in the 1970s — now often seem tall by American standards. And that casual observation matches what careful researchers have found.

The data show that Americans, who in the words of a recent paper by the economic historian John Komlos and Benjamin Lauderdale in Social Science Quarterly, were "tallest in the world between colonial times and the middle of the 20th century," have now "become shorter (and fatter) than Western and Northern Europeans. In fact, the U.S. population is currently at the bottom end of the height distribution in advanced industrial countries."

This is not a trivial matter. As the paper says, "height is indicative of how well the human organism thrives in its socioeconomic environment." There's a whole discipline of "anthropometric history" that uses evidence on heights to assess changes in social conditions.

For example, nothing demonstrates the harsh class distinctions of Britain in the age of Dickens better than the 9-inch height gap between 15-year-old students at Sandhurst, the elite military academy, and their counterparts at the working-class Marine School. The dismal working and living conditions of urban Americans during the Gilded Age were reflected in a 1- 1/2 inch decline in the average height of men born in 1890, compared with those born in 1830. Americans born after 1920 were the first industrial generation to regain preindustrial stature.

So what is America's modern height lag telling us?

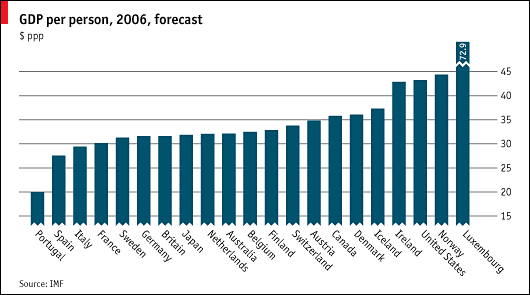
There is normally a strong association between per capita income and a country's average height. By that standard, Americans should be taller than Europeans: U.S. per capita G.D.P. is higher than that of any other major economy. But since the middle of the 20th century, something has caused Americans to grow richer without growing significantly taller.

It's not the population's changing ethnic mix due to immigration: the stagnation of American heights is clear even if you restrict the comparison to non-Hispanic, native-born whites.

And although the Komlos-Lauderdale paper suggests that growing income and social inequality in America might be one culprit, the remarkable thing is that, as the authors themselves point out, even high-status Americans are falling short: "rich Americans are shorter than rich Western Europeans and poor white Americans are shorter than poor Western Europeans."

We seem to be left with two main possible explanations of the height gap.

One is that America really has turned into "Fast Food Nation."

"U.S. children," write Mr. Komlos and Mr. Lauderdale, "consume more meals prepared outside the home, more fast food rich in fat, high in energy density and low in essential micronutrients, than do European children." Our reliance on fast food, in turn, may reflect lack of family time because we work too much: U.S. G.D.P. per capita is high partly because employed Americans work many more hours than their European counterparts.

A broader explanation would be that contemporary America is a society that, in a variety of ways, doesn't take very good care of its children. Recently, Unicef issued a report comparing a number of measures of child well-being in 21 rich countries, including health and safety, family and peer relationships and such things as whether children eat fruit and are physically active. The report put the Netherlands at the top; sure enough, the Dutch are now the world's tallest people, almost 3 inches taller, on average, than non-Hispanic American whites. The U.S. ended up in 20th place, below Poland, Portugal and Hungary, but ahead of Britain

Whatever the full explanation for America's stature deficit, our relative shortness, like our low life expectancy, suggests that something is amiss with our way of life. A critical European might say that America is a land of harried parents and neglected children, of expensive health care that misses those who need it most, a society that for all its wealth somehow manages to be nasty, brutish — and short.

I'm glad that Professor Krugman has the means to travel in Europe this summer given how much both the Euro and the British Pound have appreciated against the dollar.


Summer Session Extra Credit: Which country has the world's tallest people? If you are the first Summer Session student to send me an e-mail at kwoodward@saddleback.edu with the answer, you will be rewarded with two extra credit Discussion Board points. Only one blog extra credit question per student can be answered in any given week for Discussion Board extra credit


Monday, April 16, 2007

Is their green in going macro green?


In an earlier blog entry, I suggested that The World is Flat by Thomas Friedman may be one of the most important books that you could read in college. Now Thomas Friedman is back with some further ideas on how to sustain the long run growth of our economy.

Check out Thomas Friedman's cover story on the “Power of Green” in yesterday's New York Times Magazine. According to Friedman: “The bottom line is this: Clean-tech plays to America’s strength because making things like locomotives lighter and smarter takes a lot of knowledge — not cheap labor. That’s why embedding clean-tech into everything we design and manufacture is a way to revive America as a manufacturing power.”

Here is a video interview with Tom Friedman on how America can regain its international stature by taking the lead in alternative energy and environmentalism. Or if you prefer an audio interview with Friedman on his proposed green makeover for the economy, click here.

Thursday, April 12, 2007

California Dreaming: Green is Good Econ for Arnold


If California was a separate economy in would rank among the top ten economies in the country. Increasingly it is pursuing macro policies that are different than the United States government based in Washington. Our governor made the cover of Newsweek this week for his lead on environmental issues.

The ‘Governator' likes to call California a nation-state with its own economy. Here is an interesting quote from Mr. Schwarzenegger reported in the recent Newsweek interview:
“What we do here will have such a huge impact. We have such an unbelievable influence on the rest of the globe. We are a nation-state. We are the sixth largest, seventh largest economy in the world. We make our own deals with countries, with Japan, with China and Canada. We rely on the federal government, but we are also relying on ourselves. We're acting as a new country. "

For a provocative podcast conversation among some stellar economists on the short run and long run prospects for California’s economy, click here. There are lots of ideas in this Forum for your Discussion Board Post.

Extra Credit: Here is some extra credit for all of you budding accountants out there. What is the AMT? Why is your professor (and many other folks) grumpy about the AMT? If you are the first student to send me an e-mail (kwoodward@saddleback.edu) with the answer, you will be rewarded with two points that will be added to your Discussion Board Extra Credit Account on Blackboard. Remember to cite your source(s). Only two points in extra credit can be earned in any given week from the blog questions.

Wednesday, November 08, 2006

Is Japan a global cool pop power?


Japan has the world’s second or third largest economy depending on whether you adjust its GDP for purchasing power parity (PPP). Last summer I was lucky to get a grant to study the Japanese economy and society for a few weeks. It was a fascinating experience. I learned a lot about bubbles and the problems faced by an aging society.

Japan’s economy was once a world-beater. Twenty years after its defeat in World War II, Japan had emerged as the world’s second-largest economy and a major exporter of autos, consumer electronics, semiconductors and other sophisticated products. During the economic miracle from the 1950’s to 1980’s (“Rising Sun”), Japan evolved into the most productive manufacturing economy in the world. During the 1980’s books and studies extolled Japan as a paragon of the modern global economy, and Japan seemed on the verge of surpassing the United States as the world’s dominant power.

No country in modern history has moved so quickly from worldwide admiration to dismissal as did Japan in the 1990’s, as the bubbles in its stock and real estate markets popped big time. By any macro measure, the 1990s were a disaster for the world's second-largest economy. Macroeconomists asked how could a once-dynamic economy experience such a long period of meager growth? While the Japanese economy stagnated, Japan lent hundreds of billions of dollars to America helping to fuel the economy here.

Recently a number of more upbeat statistics and reports on Japan’s economy have begun to appear, suggesting the country may finally be recovering from its “lost decade.” However, last year Japan’s population saw its first decline in peacetime since records have been kept. The government predicts that the Japanese population of nearly 128m will fall to just over 100m by the middle of the century.

I have come across some good online resources that deal with recent developments in Japan. American RadioWorks has an entertaining program on Japan's Pop Power that you can access online. To many young people around the world, the capital of pop culture is Tokyo, not New York or LA.

On the other hand, Michael Zielenziger's new book, Shutting Out the Sun: How Japan Created Its Own Lost Generation, offers a pessimistic perspective on current Japan. He argues that Japan has not recovered from the economic stagnation of the 1990s, and he describes an tradition based economy now “jeopardized by disaffected youth.”

Extra Credit: What is purchasing power parity, and why is the concept important for macroeconomists? If you are the first student to send me an e-mail (kwoodward@saddleback.edu) with the answer, you will be rewarded with two extra credit Discussion Board points. Only two points extra credit per student can be earned in any given week from the blog questions.

Monday, November 06, 2006

Back to the Economy: Confronting America's Growth Challenges


Economic growth is one of the most important topics studied in macroeconomics. On Halloween the New America Foundation held an important conference on economic growth called “Back to the Economy: Confronting America’s Growth Challenges.” The conference featured some of the best macro minds in the business that holds diverse normative perspectives. The vdeo of the complete event is available online. The conference really brings the concepts discussed in Chapters 6 and 8 to life, and provides lots of ideas and material for Discussion Board posts.

I really like the mission statement of the New America Foundation: “Powerful forces -- from rapid technological change to massive demographic shifts, from economic globalization to the rise of new global powers -- are remaking America. Now, more than ever, our nation needs a robust public debate that does justice to the complex challenges and opportunities of this unfolding era. Instead, there is a dearth of new thinking on both sides of the political divide, and a lack of investment in developing the creative young minds most capable of crafting new public policy solutions.”

Extra Credit: If an economy is growing at 3% per year, how many years would it take the economy to double in size. If you are the first student to send me an e-mail (kwoodward@saddleback.edu) with the answer, you will be rewarded with two extra credit Discussion Board points. Only two points extra credit per student can be earned in any given week from the blog questions.

Monday, October 30, 2006

Krugman on Housing, Using Taco Sales to Predict the Economy


I had an enjoyable dinner with New York Times columnist and Princeton Econ Prof, Paul Krugman, last Thursday. I also got to meet some of my colleague dismal scientists who teach at various local colleges. Much of the econotalk at dinner centered around the housing market and its effects on the macro economy. Soft landing (slow growth) versus hard landing (recession) is the question of the day for macro forecasters.

In the middle of dinner, Professor Krugman excused himself for a minute, and whipped out his laptop computer. It turns out that he was putting the finishing touches in the column in the New York Times that would appear officially in the next day’s paper. By the time I returned home from the dinner on Thursday night at 10 p.m., the column was already incorporated in the online edition of the Times, and the subject of intense debate in the blogosphere. The world is really is flat. I dream of using Web 2.0 technology to teach online from a nice beach in Thailand.

In today’s New York Times, Professor Krugman gives his take on housing in an article called: “Bursting Bubble Blues.” I am going to excerpt part of the article since to read the whole thing you have to subscribe to a service called Times Select.

Here are some excerpts from today’s Krugman piece.
“Over the last few years, most good U.S. economic news has been the result of soaring home prices. Spending on new houses created jobs and poured cash into the economy. Consumers borrowed against the rising values of existing homes and went on a buying spree, spending more than they earned for the first time since the great depression.
But the housing boom became a bubble, fueled by a surge of irresponsible bank lending, which continues even now…The question now is how much pain the bursting bubble will inflict.

Last week’s report on G.D.P. showed the first signs of serious economic damage. According to the “advance” estimates (which are often subject to major revisions), growth in the third quarter of 2006 slowed to its worst level since early 2003. A plunge in spending on residential construction, which fell at an annual rate of 17 percent, was the main culprit. But was that just a temporary setback or the beginning of something much worse?

Some say the worst is already over. Mr. Greenspan, who’s been an optimist all the way, now argues that the latest data on new-home sales and mortgage applications suggest that housing has already bottomed out. Business investment is still growing briskly, and so far consumers haven’t cut their spending. So maybe this is as bad as it gets.

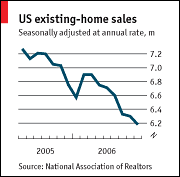
But I think the pessimists have a stronger case. There’s a lot of evidence that home prices, although they’ve started to decline, are still way out of line. Spending on home construction remains abnormally high as a percentage of G.D.P., because banks are still lending freely in spite of rapidly rising foreclosure rates.

This means that home sales probably still have a long way to fall. And you don’t want to make too much of the fact that some housing indicators have turned up; those indicators tend to bounce around a lot from month to month.

Moreover, much of the good news in the latest economic report is unsustainable at best, suspect at worst. Almost half of last quarter’s estimated growth was the result of a reported surge in automobile output, which some observers think was a statistical illusion, not something that really happened.

So this is probably just the beginning. How bad can it get? Well, you don’t have to go far to find grim forecasts: Merrill Lynch predicts that the unemployment rate will rise from 4.6 percent now to 5.8 percent by the end of next year.”

But you may object to Krugman’s analysis. We live in The OC, and The OC is different. Jon Lasner, an entertaining and knowledgeable business writer at the OC Register has an informative real estate blog that you can access here. In fact, Jon Lansner is known to read the economic tea leaves at a taco stands. See Lasner’s article: “Weak sales at Mexican fast-food chains suggest sluggish overall economy.” Meanwhile Cal State Fullerton (CSUF) economists predict that the O.C. economy will slow through 2007, and housing prices will drop. Even The OC is not immune from macro forces.

Extra Credit: Who is widely considered to be the founder of macroeconomics as a separate branch of economics? If you are the first student to send me an e-mail (kwoodward@saddleback.edu) with the answer, you will be rewarded with two extra credit Discussion Board points. Only two points extra credit per student can be earned in any given week from the blog questions.

Wednesday, October 25, 2006

The rising wealth of nations


Robert Schiller, a Professor at Yale University, is one of the most creative macroeconomists around today. Lately he has been pretty gloomy about the short run prospects for the U.S. economy in part because of the unwinding of “irrational exuberance” in the housing market. While waiting for the Fed announcement today, I came across this interesting piece that was written by Schiller and was published in the Japan Times. I was surprised that Shiller has an optimistic outlook for worldwide GDP growth in coming decades:

The rising wealth of nations

By ROBERT J. SHILLER

NEW HAVEN, Connecticut -- The new Penn World Table, Version 6.2, comparing standards of living across countries, has just been released. The latest figures are for 2004, and, because of data lags, not all countries are included. Yet these numbers are valuable because they are of exceptional quality and they correct systematically for relative price differences across countries, which sometimes leads to surprising results.

Among the 82 countries for which 2004 data are now available, there is good news: Real per capita gross domestic product rose by an average of 18.9 percent between 2000 and 2004, or 4.4 percent per year. People generally were a lot better off than they were just a few years earlier. At that rate, real per capita GDP will double every 16 years.

Many people who could not afford a car in 2000 had one in 2004, and people who could afford only one car in 2000 had two. People who could not afford to send their children to a good school or college could. And so it was with many different goods and services that people consume.

One surprise is that there was relatively little change in the ranking of countries by real per capita GDP after 2000. Despite all the talk about the Chinese economic miracle, China's ranking rose only slightly, from 61st (out of 82 countries in 2000) to 60th in 2004 -- even though per capita real GDP grew by 44 percent between 2000 and 2004, or 9.6 percent a year, the highest of the major countries.

The reason China did not rise higher is that other countries were growing too, and because the gaps between countries were enormous. The range between the poorest and the richest countries in the world is a factor of more than 100. The average real per capita GDP of the top 25 percent of countries is 15 times that of the bottom 25 percent.

Watching these countries progress is like watching a marathon. At first, one is impressed by most of the runners, almost all of whom seem to be going fast. As they pass by, all spread out, one sees that some runners seem to be gaining rapidly. And yet they do not often overtake one another, because the distances between them are so large. Indeed, other runners are out of sight, perhaps miles ahead.

China isn't the only success story. Other big winners in terms of real per capita GDP between 2000 and 2004 were Lithuania (up 48 percent), Romania (up 41 percent), Estonia (up 40 percent), Chile (up 33 percent), Hungary (up 32 percent), Greece (up 31 percent), New Zealand (up 28 percent), Australia (up 25 percent), South Korea (up 23 percent), Ireland (up 23 percent), South Africa (up 23 percent), and Nigeria (up 22 percent).

Some of the worst performers among the major countries were Israel (a beleaguered country, with real per capita GDP up only 2 percent between 2000 and 2004) and Argentina (hit by a terrible financial crisis in 2001-2002, up only 9 percent between 2000 and 2004).

Economic performance in several Latin American countries was relatively weak in this period, with Uruguay's real GDP per capita actually recording a fall by a fraction of a percent. But the overall picture was amazingly good. If such growth rates continue, we will see relatively poor countries like India, Indonesia, the Philippines or Nicaragua reach the average levels currently enjoyed by advanced countries in 50 years. But, of course, they will not have caught up with these countries, for those countries will have moved ahead too.

It is hard to imagine now what that world will be like with a doubling or quadrupling of just about every country's GDP. What will all these countries do with all that money?

In 1958, the economist John Kenneth Galbraith wrote the best-selling book "The Affluent Society," in which he argued that the advanced world as typified by the United States had by that year finally emerged from "grim scarcity," when dire necessity dictated our lives, to a "world of affluence."

He wrote: "So great has been the change [in standards of living] that many of the desires of the individual are no longer even evident to him. They become so only as they are synthesized, elaborated and nurtured by advertising and salesmanship, and these, in turn, have become among our most important and talented professions."

Real per capita GDP in the United States is now three times higher than it was in 1958. What have people been spending all that extra money on? Is it all dictated by advertisers and salesmen who are inventing needs?

According to my calculations comparing 1958 and 2005 data from the U.S. Department of Commerce, Americans spent 27 percent of the huge increase in income between 1958 and 2005 on medical care, 23 percent on their homes, 12 percent on transportation, 10 percent on recreation, and 9 percent on personal business activities.

The kinds of things that advertisers and salesmen typically promote were relatively unimportant. Food got only 8 percent of the extra money, clothing only 3 percent, and personal care 1 percent.

Unfortunately, idealistic activities also received little of the extra money: 3 percent for welfare and religious activities, and a similar share for education. Thus most of the extra money was spent on health, a nice home, travel and relaxation, and doing a little business.

Maybe that is the way it will be around the world. As long as we can keep worldwide growth going at its current rate, billions of people can look forward to the same kind of improvement. And that should be truly inspirational.”

Robert J. Shiller is professor of economics at Yale University, chief economist at MacroMarkets LLC, which he cofounded (see macromarkets.com), and author of "Irrational Exuberance and the New Financial Order: Risk in the 21st Century." Copyright Project Syndicate 2006 (www.project-syndicate.org )

Read Chapters 6 and 8 in your text for more information on economic growth.

Extra Credit: What major country had the fastest growth in its standard of living between 2000-2005? If you are the first student to send me an e-mail (kwoodward@saddleback.edu) with the answer, you will be rewarded with two extra credit Discussion Board points. Only two points extra credit per student can be earned in any given week from the blog questions.


Friday, October 13, 2006

Nobel Peace Prize goes to Economist


U.S. trained economist Muhammad Yunus and the Grameen Bank were awarded the Nobel Peace Prize for their efforts to help "create economic and social development from below" in Bangladesh by developing a system of small-scale loans (microcredit) that has helped millions people escape the grind of poverty.

Microcredit is the extension of small loans, typically $50 to $100, to entrepreneurs too poor to qualify for traditional bank loans. Grameen Bank, founded by Mr. Yunus, provides credit to "the poorest of the poor" in Bangladesh, without any collateral, according to the Grameen Bank web site.

According to the Nobel press release: “Micro-credit has proved to be an important liberating force in societies where women in particular have to struggle against repressive social and economic conditions. Economic growth and political democracy can not achieve their full potential unless the female half of humanity participates on an equal footing with the male."

The Marginal Revolution blog writes that: “This is a wonderful choice. The funny thing is, they never would have considered this guy for the Economics prize”, although I would bet he has done more to reduce poverty than anyone who has won the Economics prize.

You can read the story of Professor Yunnus and micro credit on page 207 (Chapter 8) of your text book (highly recommended reading) or on Wikipedia ,or on CNN or wherever you want in cyberspace.

The choice of Dr. Yunus to win the Nobel Peace Prize seems like an excellent choice to me. “Lasting peace can not be achieved unless large population groups find ways in which to break out of poverty.”

Extra credit: If you are the first student to send me an e-mail (kwoodward@saddleback.edu) identifying the name of the U.S. university where Professor Yunnus taught economics, you will be rewarded with two extra credit points.